US Midterm Gridlock: Why Long-Term Treasury Yields Are Stuck in a High-Range Trap
Cointime reports: Recent declines in US Treasury yields are partly attributable to the “divided government” outcome following the midterm elections. In this environment, passing large-scale fiscal stimulus legislation has become significantly harder, and elevated yields themselves now act as a real constraint on fiscal overexpansion. Moreover, partisan political maneuvering is normalizing mutual vetoes, further obstructing major fiscal bills.
However, the absence of large-scale stimulus does not mean US fiscal policy will pivot to substantive austerity—under current political conditions, austerity is equally difficult to implement. The core disagreement between the parties is not whether to expand fiscally, but where to direct spending. Democrats favor green energy investment, while Republicans oppose it and seek to cut related subsidies; on defense spending, the two parties also clash fundamentally over resource allocation for Ukraine aid versus Iran strategy. Consequently, a meaningful improvement in the US fiscal position is unlikely.
Fiscal Deterioration Slows, but Political Risk Intensifies
At the macro level, the pace of US debt and deficit expansion is expected to slow—i.e., the second derivative declines, not the total. More critically, the complex political environment will trigger a series of administrative battles that amplify volatility in Treasury yields.
First, the FY2027 budget faces deadlock. None of the 12 appropriations bills have passed, and a short-term continuing resolution only funds the government until mid-December. Disagreements over urgent spending, including defense, are hard to resolve quickly given geopolitical stalemates (e.g., Russia-Ukraine, US-Iran). Although Republicans aim to finalize the budget via reconciliation before the new Congress convenes in January, Democrats will surely use this to extract concessions, making a delay highly likely. Historical experience suggests a non-negligible risk of another government shutdown after mid-December.
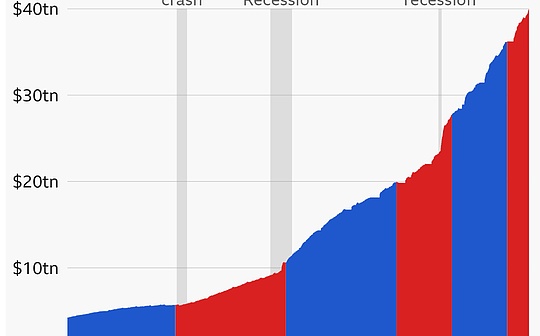
Second, the debt ceiling cliff is approaching. The $41 trillion debt ceiling is expected to be hit in May-June next year or even earlier. Some Republicans want to include a debt ceiling hike in the year-end reconciliation package to secure fiscal space, but Democrats will fiercely resist. Once the new debt ceiling negotiations begin next year, with a new election cycle approaching, the parties’ roles and demands will reverse, making the showdown unprecedentedly intense. With both debt levels and yields high, further raising the ceiling would place enormous pressure on the US economy.
Third, long-end supply pressure persists. Dense fiscal and debt ceiling battles will be sudden risk sources for bond market volatility, continuously raising uncertainty. The Treasury’s upcoming quarterly refunding announcement (QRA) also warrants caution. Driven by massive financing needs, long-bond issuance will face upward pressure. As expectations for increased issuance are repeatedly delayed and accumulated, the market’s patience is being gradually exhausted.
Outlook: No Trend Reversal, High-Range Volatility Likely
In conclusion, constrained by intensified political games and long-bond supply pressure, long-term US Treasury yields lack a logical basis for a significant decline or a sustained downtrend. They are unlikely to see a trend reversal and will probably remain in a high-range oscillation, with the possibility of short-term upward breaks triggered by sudden events.