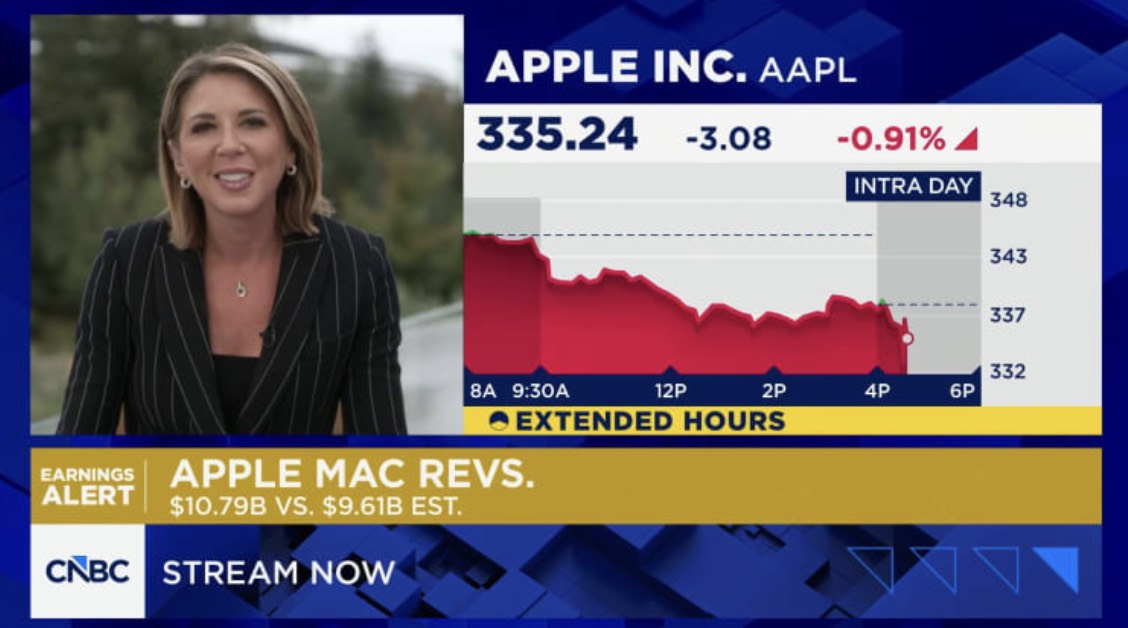
Apple Q4 Beat Fails to Lift Stock as Margin Guidance and Holiday Cost Concerns Weigh
Apple reported fourth-quarter results that exceeded Wall Street expectations, yet the stock fell 4.58% in extended trading. The disconnect stems not from the quarter just ended but from the guidance for the crucial December period, where gross margin is projected to decline to 45%-46% and operating expenses are set to grow 11%-13%, outpacing revenue growth.
Guidance Takes Center Stage
Investors zeroed in on the forward outlook. The implied gross margin range of 45%-46% represents a notable step down from recent levels, reflecting a mix shift toward lower-margin products and services, as well as anticipated cost pressures from component pricing and promotional activity. Meanwhile, operating expense growth of 11%-13% — well above expected revenue growth — signals that investments in AI, services, and retail are accelerating ahead of top-line leverage.
The combination of declining margins and rising costs creates a challenging narrative for a company that has historically been valued for its earnings stability. When both gross margin and expense trends turn unfavorable simultaneously, the market tends to re-rate the stock lower, even if the current quarter was solid.
Holiday Quarter Under Scrutiny
The December quarter is Apple’s most important period, typically accounting for a disproportionate share of annual profit. This year, the holiday season carries added uncertainty: consumer spending patterns are shifting, competition in key markets remains intense, and the product cycle may not deliver the same uplift as prior years. The guidance suggests management is preparing for a more promotional environment, which could further pressure margins.
Additionally, the services segment — a key margin driver in recent years — faces regulatory headwinds in several jurisdictions, adding another layer of risk to the profitability outlook.
Broader Implications
Apple’s guidance has ripple effects across the technology sector and the broader market. As one of the largest companies by market capitalization, its outlook influences sentiment toward consumer electronics, semiconductor suppliers, and the Nasdaq more broadly. The stock’s post-earnings decline underscores how sensitive investors have become to any sign of margin erosion in a higher-for-longer interest rate environment.
For crypto-linked equities, Apple’s results are a reminder that even mega-cap tech is not immune to cost pressures. Risk appetite could remain cautious until clearer evidence emerges that margin trends are stabilizing.
Forward-Looking Perspective
Looking ahead, the key question is whether Apple can offset margin pressure through pricing power, services growth, and cost discipline. The company’s ability to manage expenses while continuing to invest in long-term growth areas — including AI and spatial computing — will be critical. If the holiday quarter delivers revenue in line with expectations but margins come under further pressure, the stock could face additional downside. Conversely, any upside surprise on margins or expense control would likely be rewarded, given the low bar set by the guidance.
Investors will also watch for commentary on demand trends in China and other key markets, as well as any updates on regulatory developments affecting the services business. For now, the market has voted: a beat is not enough when the forward picture dims.